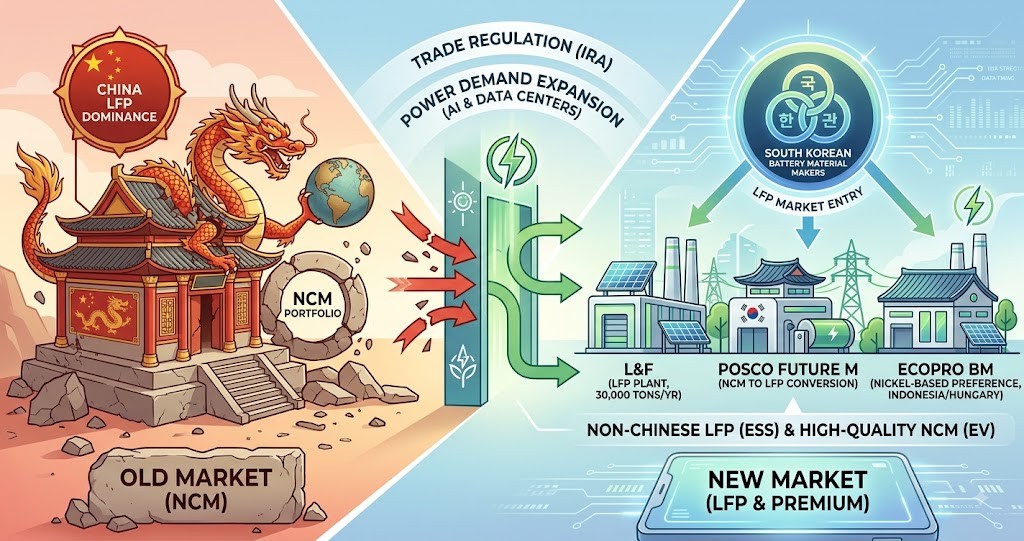
米国のインフレ削減法(IRA)による貿易規制や、生成AI・データセンター増設に伴う電力需要拡大を背景に、韓国のバッテリー素材メーカーが中国の独壇場であったリン酸鉄リチウム(LFP)正極材市場へ相次いで参入しています。従来の三元系(NCM等)中心のポートフォリオから、安価で安定性の高いLFPへ事業範囲を広げる各社の動向と、最新の関連市場情報をまとめました。
1. 韓国バッテリー素材企業のLFP市場参入の動向
参入の背景:米国の対中規制とESS需要の急増
- 米国のサプライチェーン排除: 米国の外国懸念機関(FEOC)規制などにより、中国製素材を使用したバッテリーが税額控除から排除されつつあります。これにより、北米市場向けに韓国製の非中国系LFP素材に対する需要が急増しています。
- データセンター向けESSの需要拡大: AIの普及やデータセンター増設に伴い、エネルギー貯蔵装置(ESS)向け電池の需要が拡大しています。重量や容積の制約が少ないESS用途では、コストパフォーマンスと安全性に優れたLFP正極材が強く求められています。
各社の戦略的対応
- L&F: 大邱(テグ)に年間生産能力 30000トン 規模のLFP専用工場を竣工し、7-9月期より量産を開始。北米ESS市場向けの供給網を先行構築しています。
- ポスコフューチャーM: 浦項(ポハン)工場にある既存の三元系正極材ラインの一部をLFP用に転換し、年末からの量産を目指すほか、別途LFP専用工場の建設を進めています。
- エコプロBM(独自路線): 4000トン 規模の試作ラインを備えつつも、主力の三元系正極材の競争力強化を優先。インドネシアでのニッケル製錬投資やハンガリー工場の稼働を通じて、高品質なニッケル系正極材での差別化を図っています。
2. 関連情報・事業環境の補足
- ポスコフューチャーMによる超大型長期供給契約ポスコフューチャーMは、韓国の主要バッテリーメーカーに対し、2027年から2032年までの6年間で 190000トン 以上(売上高推計 約3兆ウォン)に上る大規模なLFP正極材の長期供給合意に達しました。これは韓国素材企業として最大規模のLFP受注であり、主に北米向けESS用バッテリーに導入される見通しです。
- ポスコグループの原料シナジーによるコスト競争力中国製LFPに対する価格競争力に対抗するため、ポスコフューチャーMは親会社であるポスコの製鉄工程で発生する副産物(酸化鉄)や、アルゼンチンの塩湖から採掘する自社リチウムを活用する新工法を導入しています。原料から自前調達することで、中国企業に対抗可能なコスト構造の構築を進めています。
- 三元系(NCM)からLFP/LMFPへのポートフォリオ多角化自動車・電池メーカーの脱中国依存に伴い、これまでハイニッケル三元系(NCM/NCA)に特化していた韓国素材メーカー各社は、LFPやマンガンを添加してエネルギー密度を高めたLMFP(リン酸鉄マンガンリチウム)の開発・量産化を急ピッチで進めています。
出典:https://news.infoseek.co.jp/article/joongangilbo_353314/
ESS Market Becomes the Main Battleground: Survival Strategies for South Korean LFP Cathode Manufacturers Capitalizing on the Anti-China Push
Against the backdrop of trade restrictions under the US Inflation Reduction Act (IRA) and growing electricity demand driven by generative AI and data center expansions, South Korean battery material manufacturers are making a series of moves into the lithium iron phosphate (LFP) cathode material market, which was once dominated by China. Below is a summary of recent developments as companies expand their business scope from traditional nickel-based ternary chemistries (such as NCM) to lower-cost, highly stable LFP, along with the latest related market insights.
The Korea Times他 1 件
1. Trends in South Korean Battery Material Companies’ Entry into the LFP Market
Background of Entry: US Regulations Against China and Surging ESS Demand
- US Supply Chain Exclusion: Regulations such as Foreign Entity of Concern (FEOC) rules under US policy are excluding batteries using Chinese materials from tax credits. Consequently, demand for non-Chinese, South Korean-made LFP materials targeting the North American market is surging.
- Expanding Demand for Data Center ESS: With the proliferation of AI and the expansion of data centers, demand for batteries used in Energy Storage Systems (ESS) is growing rapidly. In ESS applications, where weight and volume constraints are minimal, cost-effective and safe LFP cathode materials are in high demand. 동아비즈니스리뷰
Strategic Responses by Company
- L&F: Completed an LFP-dedicated plant with an annual capacity of 30000 tons in Daegu, beginning mass production in Q3 (July–September). The company has proactively established a supply chain targeting the North American ESS market.
- POSCO Future M: Converted part of its existing ternary cathode material production line at its Pohang facility to LFP production, aiming for mass production by the end of the year, while also constructing a separate, dedicated LFP plant. Aju Press他 1 件
- EcoPro BM (Independent Path): Operating a 4000-ton pilot line while prioritizing the competitiveness of its core ternary cathode materials. The company plans to differentiate itself through high-quality nickel-based cathode materials by expanding investments in Indonesian nickel smelters and scaling up operations at its Hungary cathode plant.
2. Supplementary Context and Business Environment
- Massive Long-Term Supply Deal by POSCO Future M: POSCO Future M reached a large-scale, long-term supply agreement with a major South Korean battery maker to deliver over 190000 tons of LFP cathode materials (valued at an estimated 3 trillion won) over six years from 2027 to 2032. This represents the largest LFP order secured by a South Korean material company, with materials expected to be deployed primarily in batteries for North American ESS. The Korea Times
- Cost Competitiveness via POSCO Group Raw Material Synergies: To compete on price against Chinese LFP, POSCO Future M is adopting new manufacturing processes that utilize steelmaking by-products (iron oxide) from parent company POSCO, as well as lithium sourced from the group’s brine lake operations in Argentina. Sourcing raw materials internally enables the company to establish a cost structure capable of competing with Chinese firms. 동아비즈니스리뷰
- Portfolio Diversification from Ternary (NCM) to LFP and LMFP: As automakers and battery manufacturers shift away from Chinese dependence, South Korean material suppliers that previously specialized in high-nickel ternary chemistries (NCM and NCA) are rapidly accelerating the development and mass production of LFP and LMFP (lithium manganese iron phosphate), which adds manganese to increase energy density.
コメント