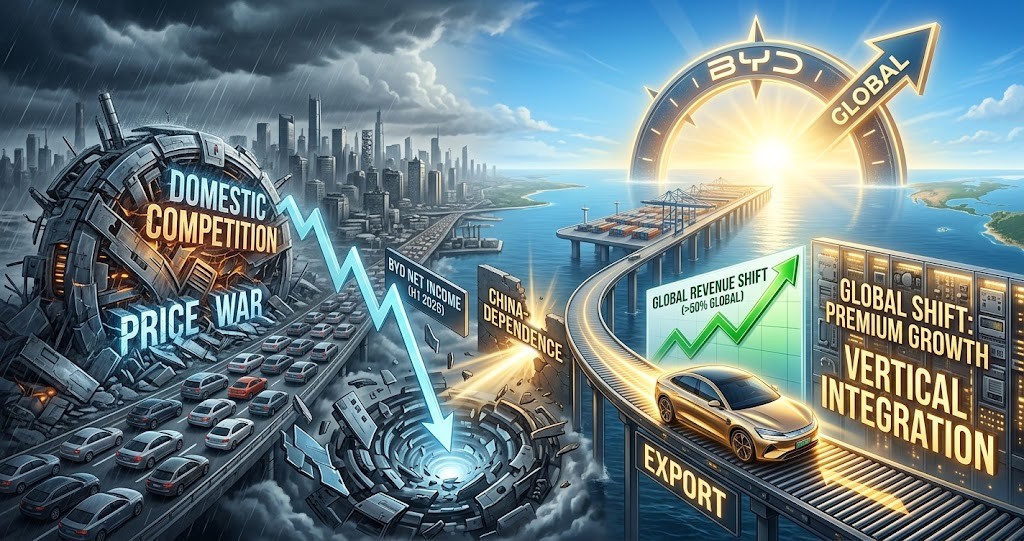
中国の新エネルギー車(NEV)大手・比亜迪(BYD)が発表した2026年1〜6月期決算は、中国国内市場での熾烈な価格競争(「内巻」と呼ばれる過剰競合)の影響を受け、上半期全体としては減収減益となりました。
しかしその一方で、海外輸出の急伸やプレミアムブランドの成長、徹底した部品の垂直統合(自社生産)によるコスト削減効果により、第2四半期(4〜6月期)単独では5四半期ぶりの純利益増へと反転を果たしました。海外売上高比率が初めて5割を超えるなど、収益構造が従来の「中国依存型」から「グローバル主導型」へ劇的に変化しつつあることを象徴する内容となっています。
BYD 2026年1〜6月期決算 要点まとめ
1. 上半期(1〜6月期)業績:価格破壊の影響で減収減益
中国国内での旧モデル値引きや安売り競争が影響し、通期としては厳しい着地となりました。
- 売上高: 3,448億元(約8兆2,800億円) / 前年同期比 7%減
- 純利益(親会社帰属): 123億元(約3,000億円) / 前年同期比 20.5%減
- 主な要因: 自動車・関連製品事業の減収(9%減)、為替変動による損失、国内市場での過酷な価格競争
2. グローバル展開:海外売上高が初めて中国国内を突破
国内の消耗戦を避ける形で海外進出を急速に拡大し、収益の柱へ成長しています。
- NEV総販売台数: 180万8,500台
- 輸出台数: 79万2,000台 / 前年同期比 67.8%増
- 海外販売台数(6月単月): 17万4,897台(過去最高を更新)
- 海外売上高: 1,813億元(約4兆3,500億円) / 前年同期比 34%増
- 全体の約53%を占め、初めて中国本土の売上高を上回った。
- 通期目標の上方修正: 年初の150万台から 170万〜180万台 へ引き上げ。
3. 高級車シフト:高付加価値ブランドの貢献
低価格帯依存からの脱却を目指し、利益率の高いブランドの展開を強めています。
- 対象3ブランド: 高級オフロード「方程豹(Fangchengbao)」、高級EV「騰勢(Denza)」、高級セダン「仰望(Yangwang)」
- 上半期販売台数: 合計22万8,000台(前年同期比 61%増)
- 構成比: 全販売台数に占める割合が 12.8% へ上昇。
4. 第2四半期(4〜6月期)の底打ち:5四半期ぶりの増益
コストダウンと構成比の変化により、収益性が急速に回復を見せました。
- 売上高: 約1,946億元(約4兆6,700億円) / 前年同期比 3.2%減
- 純利益: 約82億元(約2,000億円) / 前年同期比 30%増(5四半期ぶりの前年超え)
- 売上総利益率(粗利率): 18.9%(近1年で最高水準)
- 自動車事業の粗利率: 約23%(市場予想を上回る)
5. 車両単価とコスト構造の分析
新車の平均販売価格が下落したものの、自社製造ネットワークを活かした徹底的なコストカットが利益を下支えしました。
| 項目 (4〜6月期) | 金額 / 指標 | 前四半期(1〜3月期)比較 | 主な背景・要因 |
| 平均販売価格 (1台) | 約13万6,000元 (約330万円) | 約2万4,000元 低下 | 旧モデルの値引き販売、製品構成の変化 |
| 製造コスト (1台) | 10万5,000元 (約250万円) | 約1万8,000元 低下 | 量産化による規模の経済、自社部品の技術的低減 |
| 純利益 (1台) | 約7,200元 (約17万円) | 約1,400元 増加 | コスト低下幅が価格低下の影響を打ち消し吸収 |
【まとめと今後の見通し】
国内市場の泥沼化した価格競争により平均販売価格は抑制されているものの、「自社バッテリー等による高いコスト競争力」 と 「利益率の高い海外輸出・高級車販売の急拡大」 の2輪が機能し始めたことで、利益体質の強化に成功しつつあります。今後はEUをはじめとする各国での課税強化などのハードルに対し、海外目標(170万台超)を達成できるかが焦点となります。
BYD’s Dramatic Shift: Overseas Revenues Hit 53%, Overtaking Domestic Market! Exports Break Through Brutal Local Competition
In the H1 2026 financial results announced by Chinese new energy vehicle (NEV) giant BYD, overall revenues and net profit for the first half fell due to fierce domestic price wars (a hyper-competitive environment known as “neijuan” or involution).
However, driven by surging overseas exports, growth in premium brands, and cost reductions from aggressive vertical integration (in-house manufacturing), BYD turned the corner in Q2 (April–June) alone, posting its first year-on-year net profit growth in five quarters. The results highlight a dramatic evolution in BYD’s profit structure from a “China-dependent” model to a “global-driven” one, evidenced by overseas sales accounting for over 50% of revenue for the first time.
Key Takeaways: BYD Financial Results (H1 2026)
1. H1 Performance: Lower Revenue and Profit Impacted by Price Cuts
Slashing prices on older models and intense price wars in China weighed on overall results for the half-year.
- Revenue: 344.8 billion yuan (down 7% YoY)
- Net Profit (Attributable to Parent): 12.3 billion yuan (down 20.5% YoY)
- Primary Factors: 9% decline in automobile and related product revenues, foreign exchange losses, and extreme price competition in the domestic market.
2. Global Expansion: Overseas Revenue Outpaces Domestic Market
By rapidly expanding internationally to bypass domestic attrition, the overseas market has become a central growth engine.
- Total NEV Sales Volume: 1,808,500 units
- Export Sales Volume: 792,000 units (up 67.8% YoY)
- Monthly Overseas Sales (June): 174,897 units (all-time high)
- Overseas Revenue: 181.3 billion yuan (up 34% YoY)
- Accounted for approx. 53% of total revenue, surpassing mainland China for the first time.
- Full-Year Target Revision: Raised from the initial 1.5 million units to 1.7–1.8 million units.
3. Premium Vehicle Shift: High-Value Brands Drive Growth
BYD is strengthening its focus on higher-margin brands to reduce reliance on lower price segments.
- Three Core Premium Brands: Fangchengbao (off-road), Denza (luxury EV), and Yangwang (luxury sedan)
- H1 Sales Volume: 228,000 units total (up 61% YoY)
- Sales Share: Increased to 12.8% of total sales volume.
4. Q2 Bottoming Out: First Profit Growth in Five Quarters
Cost reductions and an improved product mix led to a swift rebound in profitability during Q2 (April–June).
- Revenue: ~194.6 billion yuan (down 3.2% YoY)
- Net Profit: ~8.2 billion yuan (up 30% YoY, reversing a 4-quarter decline)
- Gross Profit Margin: 18.9% (highest level in nearly a year)
- Automotive Gross Margin: ~23% (beating market forecasts)
5. Vehicle ASP and Cost Structure Analysis
Despite a decline in the average selling price (ASP) per car, aggressive cost reductions across BYD’s manufacturing network buoyed profits.
| Indicator (Q2) | Amount / Metric | QoQ Comparison (vs. Q1) | Primary Drivers & Factors |
|---|---|---|---|
| Average Selling Price (per unit) | ~136,000 yuan | Down ~24,000 yuan | Discounting on legacy models, shifts in product mix |
| Manufacturing Cost (per unit) | 105,000 yuan | Down ~18,000 yuan | Economies of scale from mass production, technology-driven component cost cuts |
| Net Profit (per unit) | ~7,200 yuan | Up ~1,400 yuan | Cost reductions successfully absorbed and offset price declines |
Summary and Outlook
While average selling prices remain suppressed by the ongoing price war in China, BYD is successfully building a more resilient profit structure powered by two growth engines: strong cost competitiveness via in-house battery production, and rapid expansion in high-margin overseas exports and luxury vehicles. Moving forward, the key focus will be whether BYD can achieve its upgraded overseas sales target (over 1.7 million units) while navigating headwinds such as higher tariffs in the EU.
コメント